Can You Buy a Home With Student Loans? | Truth & Data
Written by Graham Team · Graham Team Real Estate Advisors — Henderson & Las Vegas, NV · Contact
Wondering if you can buy a home with student loans? Discover the data-backed truth, learn how lenders view debt, and unlock your path to…
Dated: March 12 2025
Can You Buy a Home with Student Loans? Here's the Truth (and the Data)
📝 Quick Facts Inside This Post:
- 72% of people with student loans think it delays homeownership.
- You can still qualify for a mortgage with student debt.
- 32% of first-time homebuyers had student loans and still bought a home (NAR).
- Lenders care more about your debt-to-income ratio and credit health than the loan type.
- Median student loan balance among buyers: $30,000
Student loans do not automatically disqualify you from buying a home. According to a recent survey, 72% of borrowers believe student debt is holding them back from homeownership. But here's the kicker: it might not be the debt—it might be the misconception.
Let’s get real about what’s possible, and what’s just myth.
Can You Qualify for a Home Loan if You Have Student Loans?
If you’ve ever asked yourself:
- “Do I have to wait until my student loans are paid off to buy a house?”
- “Can I even qualify for a mortgage with this debt?”
You’re not alone. But here’s the reality: you might be more mortgage-ready than you think.
Yahoo Finance puts it plainly:
"Student loans don’t have to get in your way when it comes to becoming a homeowner. With the right approach and an understanding of how debt impacts your home-buying options, buying a house when you have student loans is possible."
The Data Doesn’t Lie: People Are Buying Homes With Student Debt
Let’s look at the numbers.
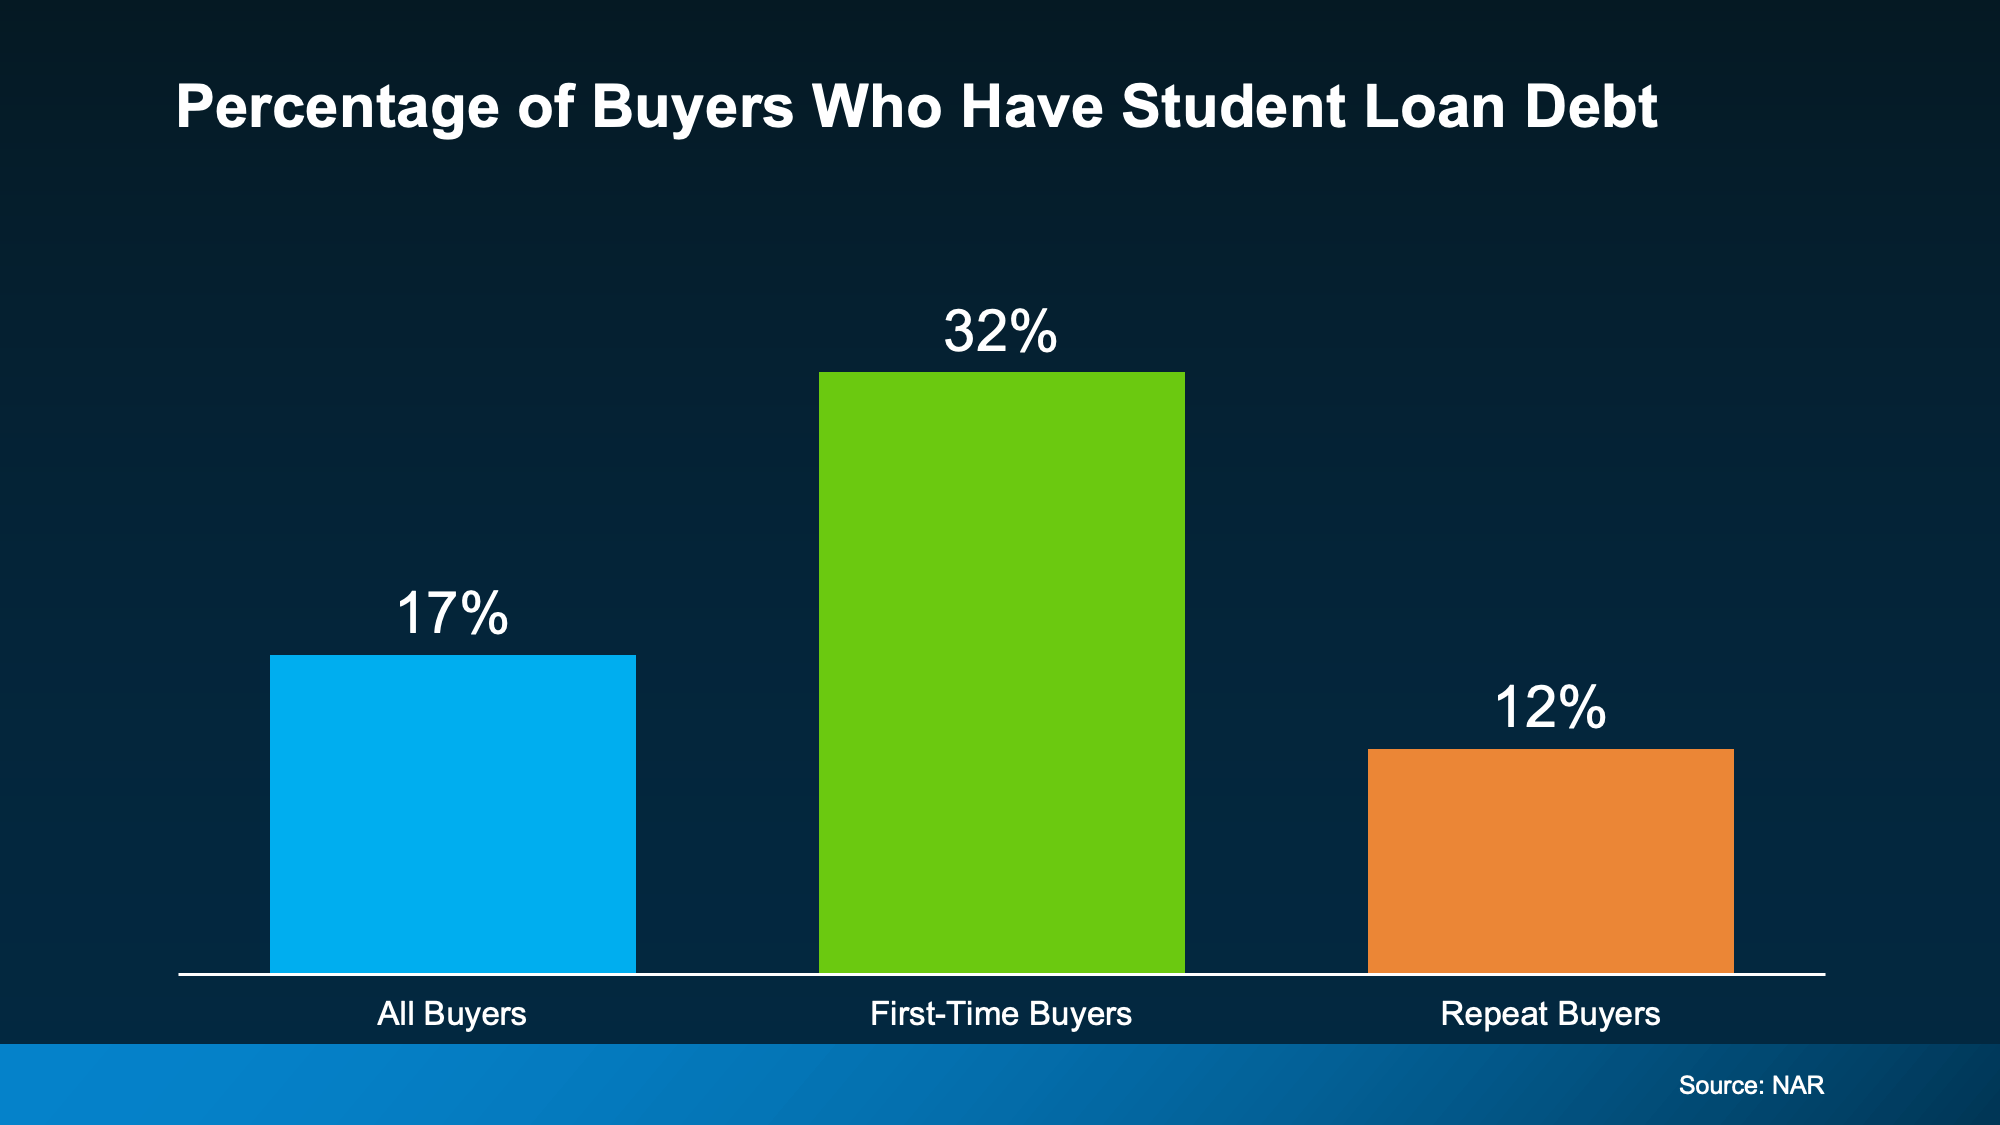
According to the National Association of Realtors (NAR):
- 32% of first-time buyers had student loan debt.
- Even among all buyers, 17% were managing student loans.
- And 12% of repeat buyers still carried that balance.
So no, student loans don’t put you in a special category of "not-ready-to-buy." In fact, you’re in good company.
Here’s What Actually Matters to a Lender
It's not the type of debt—it’s how you manage it. As Chase explains:
“Student loans usually don’t affect your ability to qualify for a mortgage any differently than other types of debt you have on your credit report, such as credit card debt and auto loans.”
If your income is stable, your credit score is decent, and your debt-to-income ratio is within reason—you could be closer to homeownership than you realize.
For context: the median student loan balance among first-time buyers is $30,000. And they’re still making it happen.
Don’t Delay Your Dream Just Because of a Balance
Here's the deal:
✅ You don’t have to wait until your loans are gone
✅ You don’t need a perfect financial profile
✅ You just need the right strategy—and the right lender
Before you write yourself off or delay your search another year, let’s talk. A quick conversation with a lender can give you a snapshot of your buying power—and maybe a green light to move forward.
Because your student loans don’t have to define your future.
Graham Team Real Estate • (702) 930-9551 • Team@grahamteamnv.com
Instagram | Facebook | YouTube | LinkedIn | TikTok
3007 W Horizon Ridge Pkwy, Ste. 210, Henderson, NV 89052
Frequently asked questions
Can you buy a home with student loans?▾
Yes, you can absolutely buy a home with student loans. According to the National Association of Realtors, 32% of first-time homebuyers successfully purchase homes while carrying student debt. Lenders do not disqualify you just for having student loans; instead, they focus on your overall credit health, debt-to-income (DTI) ratio, and history of consistent, on-time payments.
How do student loans affect my mortgage qualification?▾
Student loans affect your mortgage qualification primarily through your debt-to-income (DTI) ratio. Lenders calculate your monthly debt payments, including student loans, against your gross monthly income. Lowering your monthly student loan payment through an income-driven repayment (IDR) plan can improve your DTI, making it easier to buy a home with student debt.
What debt-to-income (DTI) ratio do lenders look for if I have student loans?▾
To buy a home with student loans, lenders typically look for a total debt-to-income (DTI) ratio of 43% or lower, though some programs allow up to 50%. This ratio includes your future mortgage payment plus existing monthly obligations like student loans, credit cards, and car payments. Keeping your DTI low increases your borrowing power.
Does being on an income-driven repayment (IDR) plan help me buy a house?▾
Yes, an income-driven repayment (IDR) plan can help you buy a home with student loans. Many mortgage programs, including FHA and Conventional loans, allow lenders to use your actual IDR monthly payment—even if it is $0—to calculate your debt-to-income ratio. This significantly increases your purchasing power compared to standard payment calculations.
Can I buy a home if my student loans are in deferment or forbearance?▾
Yes, but lenders must still factor a monthly payment into your debt-to-income ratio. If your loans are deferred, lenders typically estimate a payment using 0.5% to 1% of your total student loan balance, depending on the loan type. This means you can still buy a home with student loans even during deferment.
What credit score do I need to buy a home with student loans?▾
To buy a home with student loans, you generally need a minimum credit score of 580 for an FHA loan or 620 for a conventional mortgage. Managing your student debt by making consistent, on-time payments is one of the best ways to build the strong credit profile needed to secure favorable mortgage rates.