How FHA Loans Help First-Time Homebuyers Break Into the Market
Written by Graham Team · Graham Team Real Estate Advisors — Henderson & Las Vegas, NV · Contact
Discover how FHA loans help first time homebuyers break into market in Las Vegas. Learn about lower down payments, flexible credit, and rate savings.
Dated: May 14 2025
If buying your first home feels a little like trying to summit Everest with a backpack full of avocado toast and student debt, you’re not alone. Between high prices, rising rates, and the eternal “Do I have enough saved?” spiral, it’s no wonder many would-be buyers feel stuck.
But here's the part they don’t talk about enough: FHA loans are built for exactly this moment.
Designed with first-time buyers in mind, FHA loans exist to knock down the two biggest barriers: your down payment and your monthly payment.
Let’s unpack how they do that and why they’re one of the smartest and underutilized tools in the market right now.
Buying Your First Home Is Harder Than Ever (We Get It)
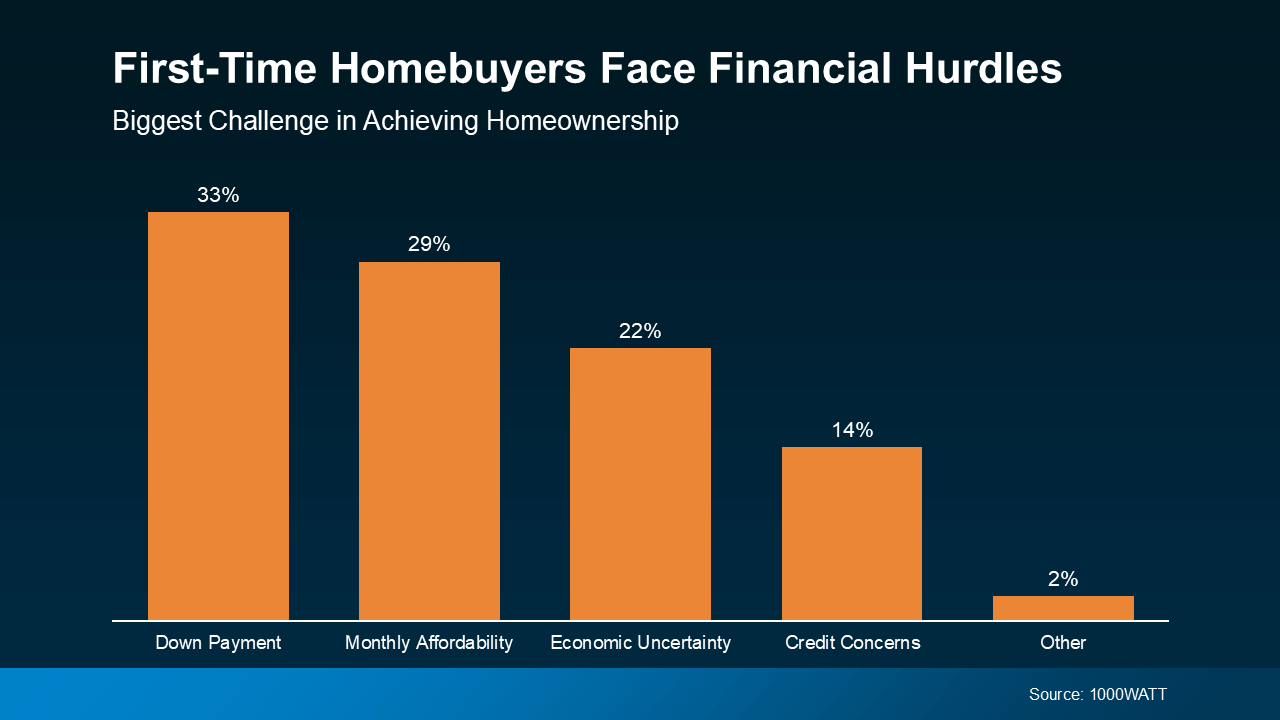
Even the most motivated buyers are feeling the pressure. According to a recent survey from 1000WATT, the top two concerns for first-timers are:
• Saving enough for a down payment
• Affording monthly mortgage payments at today’s prices and interest rates
Sound familiar?
This isn’t just about sticker shock—it’s about financial strain that can turn your homebuying dream into a very long waiting game.
FHA Loans: The Fast Track to “You’re Approved”
Here’s where the FHA (Federal Housing Administration) steps in to play hero. Their loans are specifically tailored to help people who:
– Don’t have 20% down saved (or even close)
– Might not have perfect credit
– Need flexibility on debt-to-income ratios
How flexible are we talking?
🟢 The average down payment for first-time buyers using an FHA loan is $16,000, according to Intercontinental Exchange (ICE).
🔴 Compare that to a typical $77,000 down with a conventional loan. Huge difference.
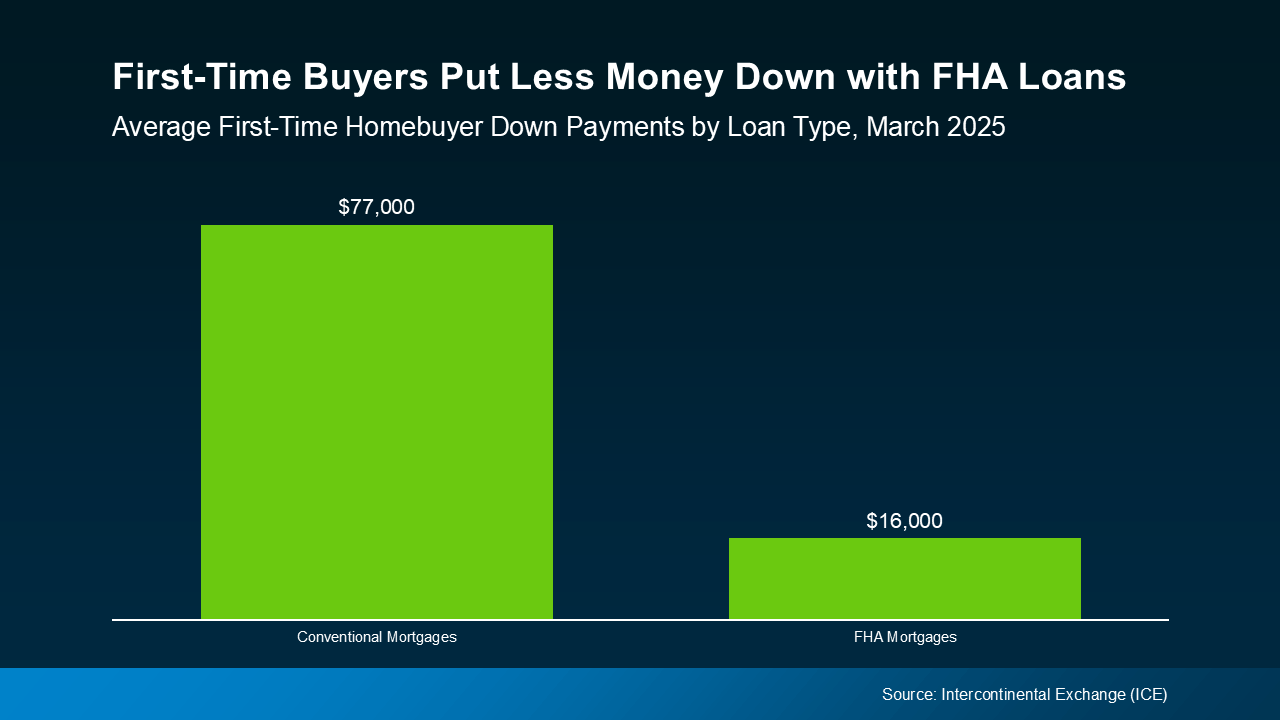
Oh, and that monthly payment that’s been haunting your dreams? Bankrate confirms that FHA rates are often slightly lower than conventional ones. That means lower upfront costs and potentially more affordable payments month to month.
If you’re still renting, you might want to check out this post on the long-term cost of renting while you're at it.
So, What’s the Catch?
There isn’t one. As long as you work with a knowledgeable lender who understands your unique financial situation. They’ll walk you through:
• How much you qualify for
• Your interest rate options
• The true monthly cost (including taxes + insurance)
• Whether an FHA loan or another program is a better fit
Pro tip: There are even local first-time buyer assistance programs that stack on top of FHA benefits.
You don’t have to do this alone and you definitely don’t have to wait. FHA loans make homeownership more accessible for first-timers who are ready but feeling overwhelmed.
✅ Smaller down payment
✅ Competitive interest rates
✅ Easier approval standards
Let’s talk about what’s possible. Want to explore your options? We can help connect with a trusted local lender today.
Graham Team Real Estate • (702) 930-9551 • Team@grahamteamnv.com
3007 W Horizon Ridge Pkwy, Ste. 210, Henderson, NV 89052
Work with the Graham Team
Planning your first home or a move to Henderson and Las Vegas? Talk with our first-time-buyer and relocation specialists, Dylan Graham and Noelle Vetter, about your budget, priorities and next steps.
Frequently asked questions
What is the main benefit of FHA loans for first-time homebuyers?▾
The main benefit of FHA loans for first-time homebuyers is accessibility. These government-backed loans require a down payment as low as 3.5% for those with credit scores of 580 or higher. This significantly lowers the upfront cost barrier compared to conventional mortgages, allowing buyers to enter the housing market much sooner.
How much down payment do I need for an FHA loan?▾
With FHA loans, you only need a 3.5% down payment if your credit score is 580 or above. If your credit score falls between 500 and 579, a 10% down payment is required. This makes FHA loans for first-time homebuyers highly attractive compared to conventional options that typically demand more upfront cash.
Can I qualify for an FHA loan with a low credit score?▾
Yes, you can qualify for an FHA loan with a lower credit score than conventional loans require. Borrowers with a credit score of 580 or higher qualify for the minimum 3.5% down payment. If your score is between 500 and 579, you can still secure an FHA mortgage with a 10% down payment.
Are interest rates lower for FHA loans compared to conventional loans?▾
Interest rates for FHA loans are highly competitive and often slightly lower than conventional mortgage rates. Because the federal government backs these loans, lenders take on less risk. This reduction in risk often translates into lower interest rates, helping first-time buyers lower their monthly mortgage payments.
Do FHA loans require monthly mortgage insurance?▾
Yes, FHA loans require a Mortgage Insurance Premium (MIP) instead of conventional private mortgage insurance (PMI). You will pay an upfront MIP fee at closing, plus annual premiums split into your monthly payments. This insurance protects the lender and is mandatory regardless of the size of your down payment.
What are the debt-to-income (DTI) requirements for FHA loans?▾
FHA loans offer highly flexible debt-to-income (DTI) ratio requirements. While lenders generally prefer a DTI ratio of 43% or lower, borrowers can often get approved with DTIs up to 50% if they have compensating factors, such as strong cash reserves, steady employment, or a higher credit score.